Imagine a leak in a pipe. Small enough that you don't notice it on any given day. Large enough that, over twenty years, it has emptied half the tank. That is tax drag. Not dramatic and visible in any single statement. Not the kind of risk that prompts an urgent call to a financial adviser. It is the kind of risk that reveals itself only at the end of a long investment horizon, when the gap between what the investor expected to have accumulated and what they can actually spend is too wide to explain away and too late to recover. Most investors know they will pay capital gains tax. What they consistently underestimate is the compounding dimension of that obligation. Tax paid today is a permanent reduction in the capital base available for future growth. And in a compounding system, the base is everything. Open any Indian equity portfolio statement. The figure at the top is pre-tax. The return percentage and the benchmark comparison are also both pre-tax. The entire infrastructure of retail investment reporting is calibrated to a number the investor will never actually receive in full. Long-term capital gains tax sits at 12.5% on equity gains above 1.25 lakh rupees for positions held beyond a year. Modest enough in isolation. Short-term capital gains tax, at 20% for exits within twelve months, is considerably more punishing for the investor who rotates frequently. Dividend income often held in portfolios as the "safe" component is now taxed at the investor's applicable income slab, which, for anyone in the upper brackets, represents a material additional drag. Layer on compliance costs, brokerage charges, and transaction friction, and the gap between the return the portfolio generates and the return the investor keeps is wider than most people have ever calculated. The investor who has never done this calculation has simply never been shown the complete picture. That omission, compounding silently over decades, is where wealth quietly disappears. Numbers make this concrete in a way that abstraction cannot. Take ₹10 lakhs invested at a nominal return of 12% annually. Left to compound undisturbed in a hypothetical tax-free environment, that corpus grows to approximately ₹93 lakhs over twenty years. Now apply a conservative effective tax drag of 2% annually — accounting for capital gains obligations, dividend tax, and the friction of compliance. The net compounding rate drops to 10%. The same corpus, over the same twenty years, now grows to approximately ₹67 lakhs. The difference is ₹26 lakhs. Not the amount of tax paid, but the amount of compounding that the tax prevented. This is the number that never appears on any statement. It accumulates in silence, transaction by transaction, year by year, in the space between what the portfolio earned and what the investor retained and redeployed. By the time it becomes visible, the opportunity to recover it has passed. The investor who turns over their portfolio frequently further accelerates this erosion. Eve
Related Stories
 Lam Research to invest Rs 10,000 Cr in India, set up first silicon component man
 Kissht parent OnEMI board approves Rs 832 crore preferential issue
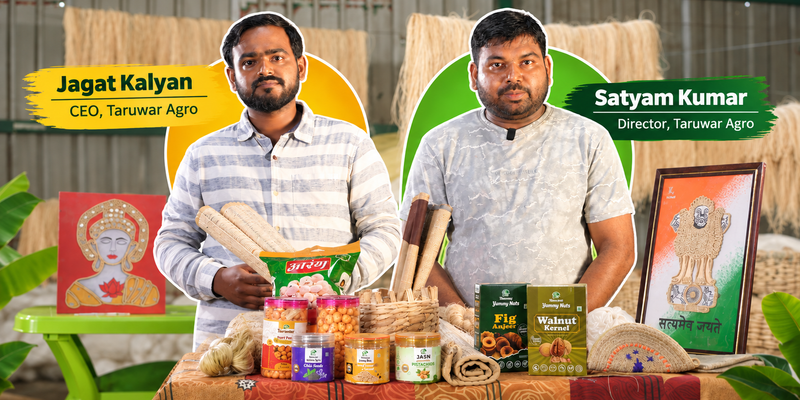 Taruwar Agro: Three Bihar Friends Built a Rs 2.5 Crore Business from Banana Wast
 Adidas Confirms Job Cuts at India Tech Hub, Nearly Half of Employees Affected