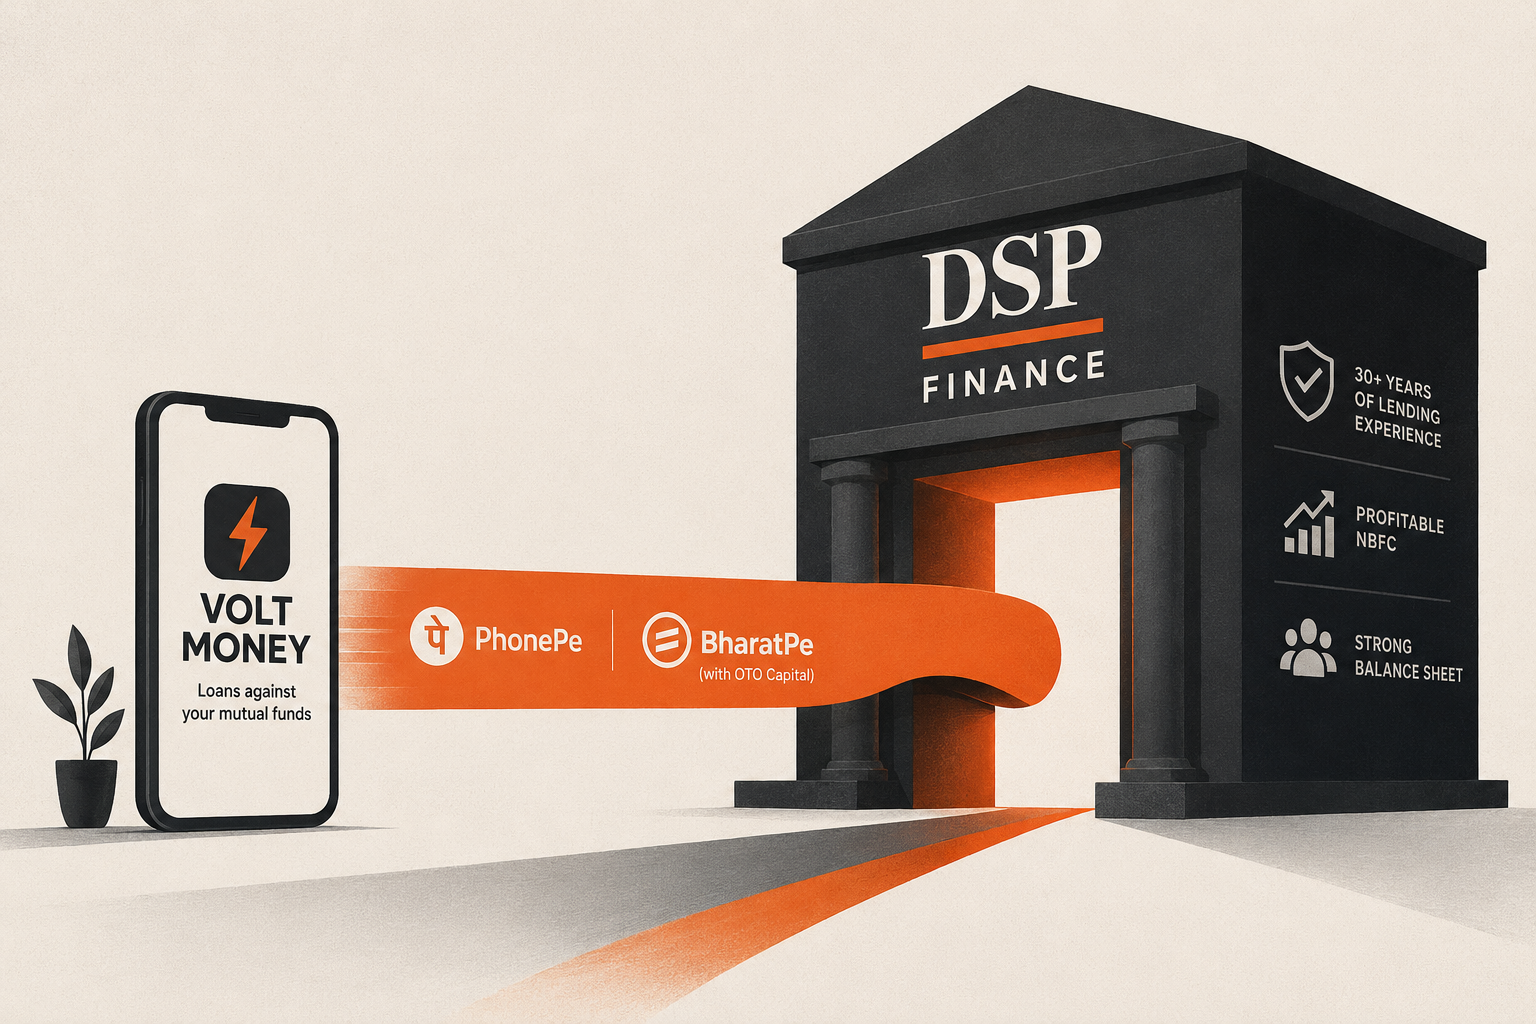
A digital lender that grew revenue 856% in a year and still lost money got folded into a 30-year-old, profitable NBFC that had been reading its books since month two. In October 2022, two months after Bharat Lamba, Ankit Agarwal and Lalit Bihani registered a company called Salter Technologies in Mumbai, the money for its first funding round came in.$1.46 million, led by two funds most people outside VC circles have never heard of, Raise and All In Capital, with cheques from a handful of angels including Snapdeal co-founderKunal Bahl. Sitting in that same cap table, in a round nobody wrote a headline about, was DSP Mutual Fund. Salter Technologies is better known by its product name:Volt Money,the app that lets you borrow against your mutual funds instead of selling them. In March 2025, DSP Finance, the NBFC arm of the DSP group, bought the company outright. Most of the coverage treated it as a straightforward acquisition story: fintech disrupts lending, legacy player buys the disruptor. The cap table tells a slightly different story. DSP wasn't a stranger who came knocking. It had been sitting inside the company fortwo and a half yearsbefore it decided to just take the whole thing. Volt Money raised twice before the acquisition, and DSP Mutual Fund showed up both times. Total disclosed equity raised across both rounds:$2.96 million. That's a small number for a company that ended up getting bought by one of India's older asset-management houses. It also means DSP had roughly two and a half years of board-level or shareholder-level visibility into Volt Money's numbers before it made the acquisition call. A source close to the deal put it plainly in trade-press coverage the week it closed: That single line is the whole story, really. Everything else is detail. Here's the part that's easy to miss if you only read the press release:DSP Finance already did this.It's been in the business of lending against mutual fund and share holdings since1996, decades before "loan against mutual funds" became a fintech buzzword. It's profitable. Its FY25 revenue was roughly$16.2 million, with a net profit of about$7.76 million, against Volt Money's FY25 revenue of$1.63 millionand a net loss of$1.17 million. So this wasn't a case of a legacy lender waking up to a category it didn't understand. DSP Finance understood the category better than almost anyone, it had run it as an old-school NBFC business for three decades. What it didn't have was Volt Money's front end: the 10-minute disbursal, the app that marks a digital lien on your mutual fund units in 15 seconds, and, more importantly, the distribution deals Volt Money had already signed. By the time of the acquisition, Volt Money had live partnerships withPhonePe(from May 2024) and, alongside OTO Capital, withBharatPe(from August 2024). That's tens of millions of app users DSP Finance would have taken years to reach on its own. I think this is the more useful way to read the deal: not "fintech gets acquired," but a